


 Alex Thompson
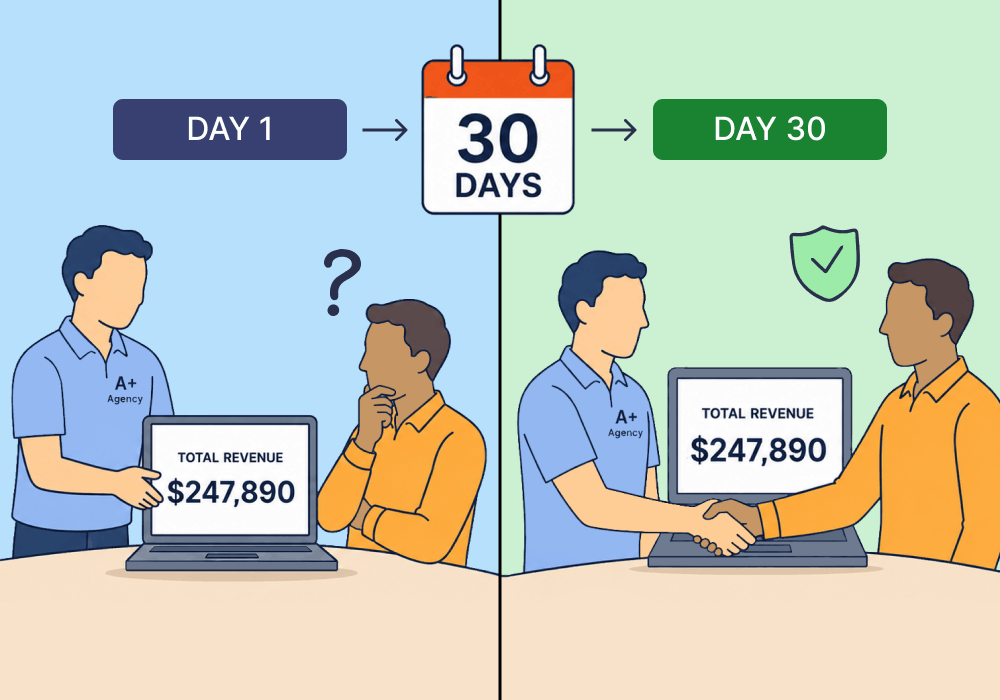
You’ve just pitched a roofing client on a revenue-based fee. Instead of charging a flat $4,000 monthly retainer, you’d earn a share of the revenue your marketing generates. The client likes the idea but pauses. “Let me think about it.”
The hesitation may not be about the price. It may be about the revenue number behind it. If the client can’t check that number, a new fee tied to it feels riskier than the flat rate they already know. They’re not ready to price the relationship from a number they don’t yet trust.
That’s the challenge a Revenue Retainer has to solve. The agency’s fee is based on the revenue its marketing generates, so both sides need confidence in the attribution before the ongoing fee is set. This article explains how a paid 30-day proof phase builds that confidence using the client’s existing campaigns and actual revenue data.
| Client says | “I’ll think about it.” |
| Client means | “I don’t believe that number yet.” |
“Let Me Think About It” May Be a Confidence Objection
When a home-services client pushes back on a revenue-based fee, it’s easy to assume the rate is too high. But lowering the price won’t solve the problem if the client doesn’t trust the revenue number behind it.
Pricing consultant David Hoos describes a software firm that proposed a $90,000 outcomes-based project. The pitch promised less reporting time, faster decisions, and an estimated revenue gain over 18 months. The client chose a cheaper hourly competitor. Hoos’s takeaway was that the firm tried to price the outcomes before the client believed they were achievable. As he puts it, “Most objections are not price objections. They’re cash flow objections, confidence objections, or scope uncertainty.”
You can see the same concern in legal services. Corporate counsel may reject alternative fees because of “the fear that if costs exceed expectations, it will reflect poorly on their judgment” (Legal Dive). A familiar billing model can feel safer even when another structure has better economics.
Existing clients can be especially anchored to the fee they already know. Years of invoices have taught them what your work is “worth” in hours, tasks, or a flat monthly amount. You can show a plumbing client that their campaigns drove $180,000 last quarter. But if they can’t open the system, trace a call to a booked job, and verify the revenue, the figure still depends on your word.
That’s the first takeaway: before you negotiate the percentage, find out whether the client believes the revenue number. If they can’t verify the basis of the fee, changing the rate won’t close the trust gap.
An outcomes-based proposal that lost to a cheaper hourly bid. The client wasn’t ready to trust the projected value.
Read the Article – Introducing the Revenue Retainer: A New Way to Price Agency Work
A Revenue Number Becomes Credible When the Client Can Verify It
The client isn’t being stubborn. If you control the attribution data and they can only see the final report, the information is uneven. They can’t trace a call to an ad, connect the lead to a booked job, and confirm the revenue themselves. So they discount the number.
Think about how that feels to a roofing owner who tracks won jobs from memory and has seen marketing promises fall short before. They don’t look at a new dashboard and assume it’s right. They think, “I’ve heard this before.” Without a way to check the figure, they’ll fall back on their existing assumptions about what marketing usually produces.
The new fee structure makes that uncertainty more important. The client already understands what a $4,000 monthly retainer costs. Replacing it with a share of an unverified number feels risky, even when your math favors the change. According to Forrester, 64% of B2B marketing leaders don’t trust how their own companies measure results. Your client may be skeptical of marketing measurement in general, not just your reporting.
You can’t talk past that information gap. You have to close it. Let the client watch the revenue number come together from their own data before you use it to set the ongoing Revenue Retainer.
| When the client can’t check itYou hold the attribution data↓The client can’t trace a call to a booked job↓So they fall back on their existing assumptions | When a new fee replaces a familiar oneAn unproven revenue-based fee competes with a flat fee they already understand≈2×the weight people often give a potential lossSo the unfamiliar option feels riskier |
Make the First 30 Days a Paid Proof Phase
Before you set the ongoing Revenue Retainer, run a paid proof phase on the client’s current marketing. Connect their data, validate attribution, measure lead quality, and compare early revenue with the forecast. You’re not launching a new strategy yet. You’re proving that the number behind the future fee can hold up.
Not every “first month” provides that proof. Researcher Luk Smeyers draws a line between a substantive discovery engagement and a generic audit. Workshops, scoring slides, and broad recommendations may give the client little they can act on. A first month built on the client’s actual data and designed to answer a business question “becomes a business asset. And business assets can and should be paid for.”
That’s why the phase shouldn’t be treated as a throwaway audit or discounted trial. It has its own deliverable: a validated view of attribution, lead quality, and early revenue. A roofing client who pays for that work and helps connect calls to campaigns is participating in a real measurement project, not sampling the agency for free.
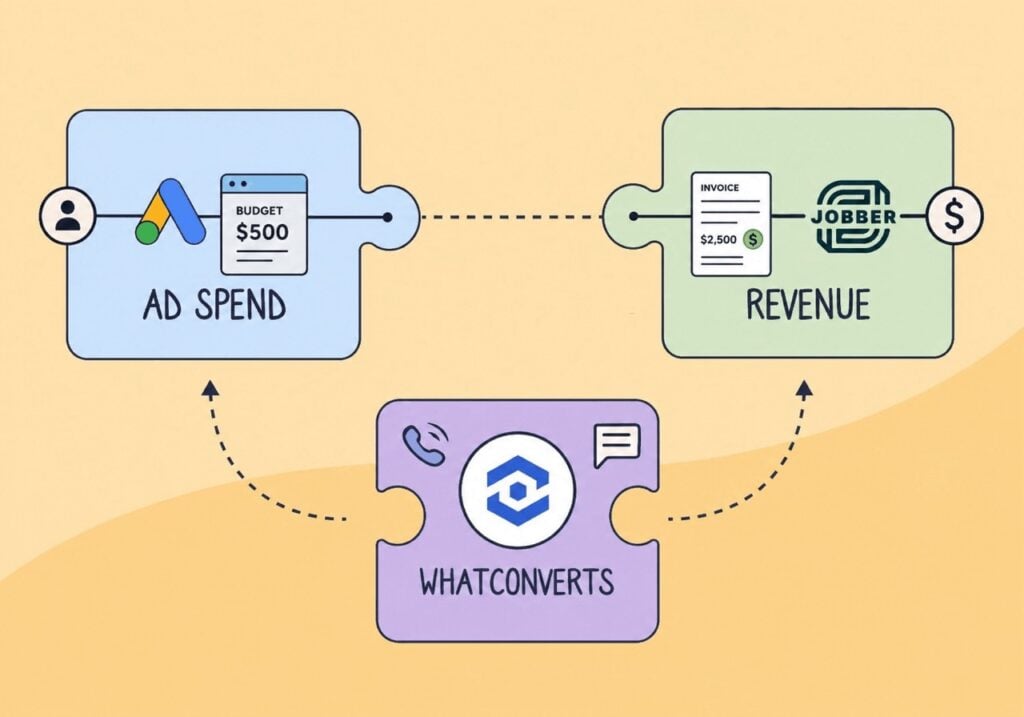
WhatConverts calls this the Forecast-and-Audit confidence phase. The forecasting tool uses the client’s goals, close rates, and industry data to help the agency estimate a Revenue Retainer. The next 30 days test the assumptions against the client’s actual data before the ongoing retainer is finalized. There’s one important requirement: the client has to connect real revenue data and stay involved. Watch for three signs that they may not be ready for the phase:
- They won’t share the access needed to connect their ad accounts, CRM, or job-tracking system
- They don’t see value in paying for the measurement work
- They won’t commit to reviewing the data with you at a midpoint check-in
Name those requirements before the work begins. A proof phase can’t build confidence if the client won’t provide the data or participate in the review.
The First 30 Days Should Answer Four Questions
The proof phase runs on the client’s current marketing. You’re checking whether the proposed revenue number is supported by traceable leads, real job outcomes, and early revenue.
Work through four steps in order.
1. Connect the data. Add tracking to the client’s current campaigns and bring calls, forms, and chats into one place through lead tracking. The first question is basic: Can both sides see the same leads in one view?
2. Validate attribution. Confirm that each lead connects to the campaign, keyword, and source that generated it. When the client asks, “How do I know marketing drove these?” you can show revenue tied back to the campaigns that produced it, one lead at a time.
3. Measure lead quality. Separate real opportunities from junk and low-intent inquiries. A price-check call isn’t the same as a $15,000 roof-replacement opportunity. Qualifying and valuing leads helps the client see which inquiries became jobs, so the revenue figure reflects actual business value.
4. Compare early revenue with the forecast. Put the first weeks of tracked, qualified revenue beside the assumptions behind the proposed retainer. The client can compare actual revenue data with the forecast. If the early results support the assumptions, the conversation can move from “Can I trust this number?” to “What should the ongoing agreement look like?”
| What you verify | The question it answers |
| 1 Connect the dataCurrent campaigns feed leads into one shared view. | “Where do my leads come from?” |
| 2 Validate attributionEach lead tied to its campaign and keyword. | “Did my marketing drive these?” |
| 3 Measure lead qualityPrice-check calls separated from booked jobs. | “Which calls became jobs?” |
| 4 Compare to forecastEarly revenue tested against the forecast assumptions. | “Are we hitting the forecast?” |
A roofing client spending $8,000 a month on Google Ads can watch you connect their campaigns, sort calls by source and value, and compare early revenue with the forecast. By week four, the number is no longer something you simply reported. It’s a figure both sides have examined.
Find the Plan That Fits: Compare WhatConverts Plans
Early Transparency Can Support a Longer Relationship
Once the client has watched the number come together from their own data, the conversation changes. You’re no longer asking them to accept a revenue figure on faith. Both sides can review the same measurement process.
Trust and transparency are also associated with longer agency relationships. According to the ANA, clients and agencies now work together for about seven years on average, up from 3.2 years in 2016. The ANA describes trust and transparency as part of the foundation for that change.
One comparison stands out. Clients without formal review periods keep their agencies for about 8.1 years on average, compared with 3.8 years for clients that conduct frequent reviews. That doesn’t prove that fewer reviews cause longer relationships; stronger relationships may simply require less formal oversight. But it does show why early confidence matters. A client who understands the measurement process from month one may need less reassurance later.
The transparency shouldn’t stop after 30 days. The client can monitor the revenue behind the retainer, with calls connected to campaigns, leads sorted by value, and results tracked over time.
That changes the quarterly review. Showing the value behind your fee is no longer a new pitch. You’re reviewing a measurement process the client already understands.
| 2016 average | 3.2 yrs | |
| 2025 average | ~7 yrs | |
| Frequent reviews | 3.8 yrs | |
| No reviews | 8.1 yrs | |
| 0 to 9 years | ||
Make the Client Part of the Proof
The client who said “let me think about it” may not need a lower rate. They may need to see the revenue figure behind the proposed fee come together from their own data.
Before you start, confirm three things:
- The client is a good fit. They generate enough leads to measure, record jobs or invoices in an accessible system, and are open to a results-based fee.
- You can connect the necessary data. You need access to the ad accounts and a way to connect leads with booked revenue. If the client can’t provide that access, explain the limitation before proposing the phase.
- You’ll price the phase as a real engagement. Define the work, deliverables, access requirements, and fee separately from the ongoing Revenue Retainer.
Then run the four steps: connect the data, validate attribution, measure lead quality, and compare early revenue with the forecast. Involve the client at each stage. Let them trace calls to sources, distinguish weak inquiries from real jobs, and compare observed revenue with the original assumptions. If the data supports the forecast, both sides can discuss the ongoing fee from a shared set of facts. If it doesn’t, revise the forecast before setting the retainer.
Start with one client that has reliable data, enough lead volume, and a willingness to participate. The goal isn’t to force a Revenue Retainer through in 30 days. It’s to find out whether the evidence supports one.
Read the Article – You Don't Have to Jump All at Once: A Practical Path to a Revenue Retainer
Ready to try the Revenue Engine for your own agency?
Get a FREE presentation of WhatConverts
One of our marketing experts will give you a full presentation of how WhatConverts can help you grow your business.
Schedule a DemoGrow your business with WhatConverts


